★★★★★
"They explained what was happening and helped us understand the next step."
Sarah M. · Google Review
Insurance claim lawyers
If your claim was denied, payment is delayed, or the offer does not cover the damage, you may still have options. We help policyholders understand the policy, the dispute, and the next step. We never represent insurance companies.
Insurance claims we handle
Denied insurance claims
Denied claims may involve coverage denials, exclusions, late-notice arguments, cause-of-loss disputes, and documentation disputes. A denial letter is a starting point for review, not always the final word.
Review my denialDelayed insurance claims
Delayed claims may involve repeated document requests, no clear answer, slow inspections, slow payment, and unclear claim status while the loss goes unrepaired.
Review the delayUnderpaid insurance claims
Underpaid claims may involve low repair estimates, partial payments, scope disputes, supplemental claims, and contractor-estimate disagreements.
Review the paymentProperty damage claims
Property claims may involve residential and commercial property, roof, water, fire and smoke, mold, storm damage, contents, and business-interruption losses.
Review property claimSerious claim-handling concerns
Concerns may involve unreasonable delay, failure to explain a denial, failure to investigate, misrepresenting policy language, or lowball settlement behavior. These issues should be attorney-reviewed.
Review claim handlingThe claim file
Save the policy, letters, estimates, photos, reports, payment explanations, and a timeline of what happened. An organized record makes it easier to understand what is missing and where the dispute began.
Policy, declarations page, endorsements, exclusions, deductibles, and duties after loss.
Claim number, insurance company letters, payment explanations, emails, texts, and call history.
Photos, videos, inspection reports, contractor estimates, mitigation records, and invoices.
What happened, when it happened, what the insurance company said, and what changed after the loss.
Common insurance company arguments
These arguments should be reviewed against the policy, facts, photos, reports, damage history, repair estimates, and the claim timeline.
Coverage depends on policy language, exclusions, endorsements, facts, and cause of loss.
Common in roof, water, plumbing, storm, and older-property claims.
Maintenance arguments should be reviewed against damage photos, history, inspections, and cause.
Pre-existing-damage arguments may turn on timing, photos, inspections, and what changed after the loss.
The dispute may involve scope, labor, materials, code items, and restoration costs.
Notice, reporting, mitigation, and claim-specific timing should be reviewed carefully.
Document requests should be organized against what the insurance company asked for and what was provided.
Deductible issues may depend on actual repair scope, hidden damage, and supplemental documentation.
How we help with insurance claims
The goal is to move from confusion to a clearer claim record, a clearer dispute, and a clearer next step.
Coverage, exclusions, deductibles, letters, payment history, and claim timeline.
Photos, estimates, reports, invoices, mitigation, repair scope, and inspections.
Denial, delay, underpayment, causation, exclusion, maintenance, pre-existing damage, or documentation issue.
Communicate, negotiate, and consider legal action when the insurance company will not resolve the claim fairly.
Meet the attorneys
David Graham Insurance Lawyers, P.A. represents homeowners, businesses, and injured people — and never insurance companies. That single choice shapes how every claim is handled.
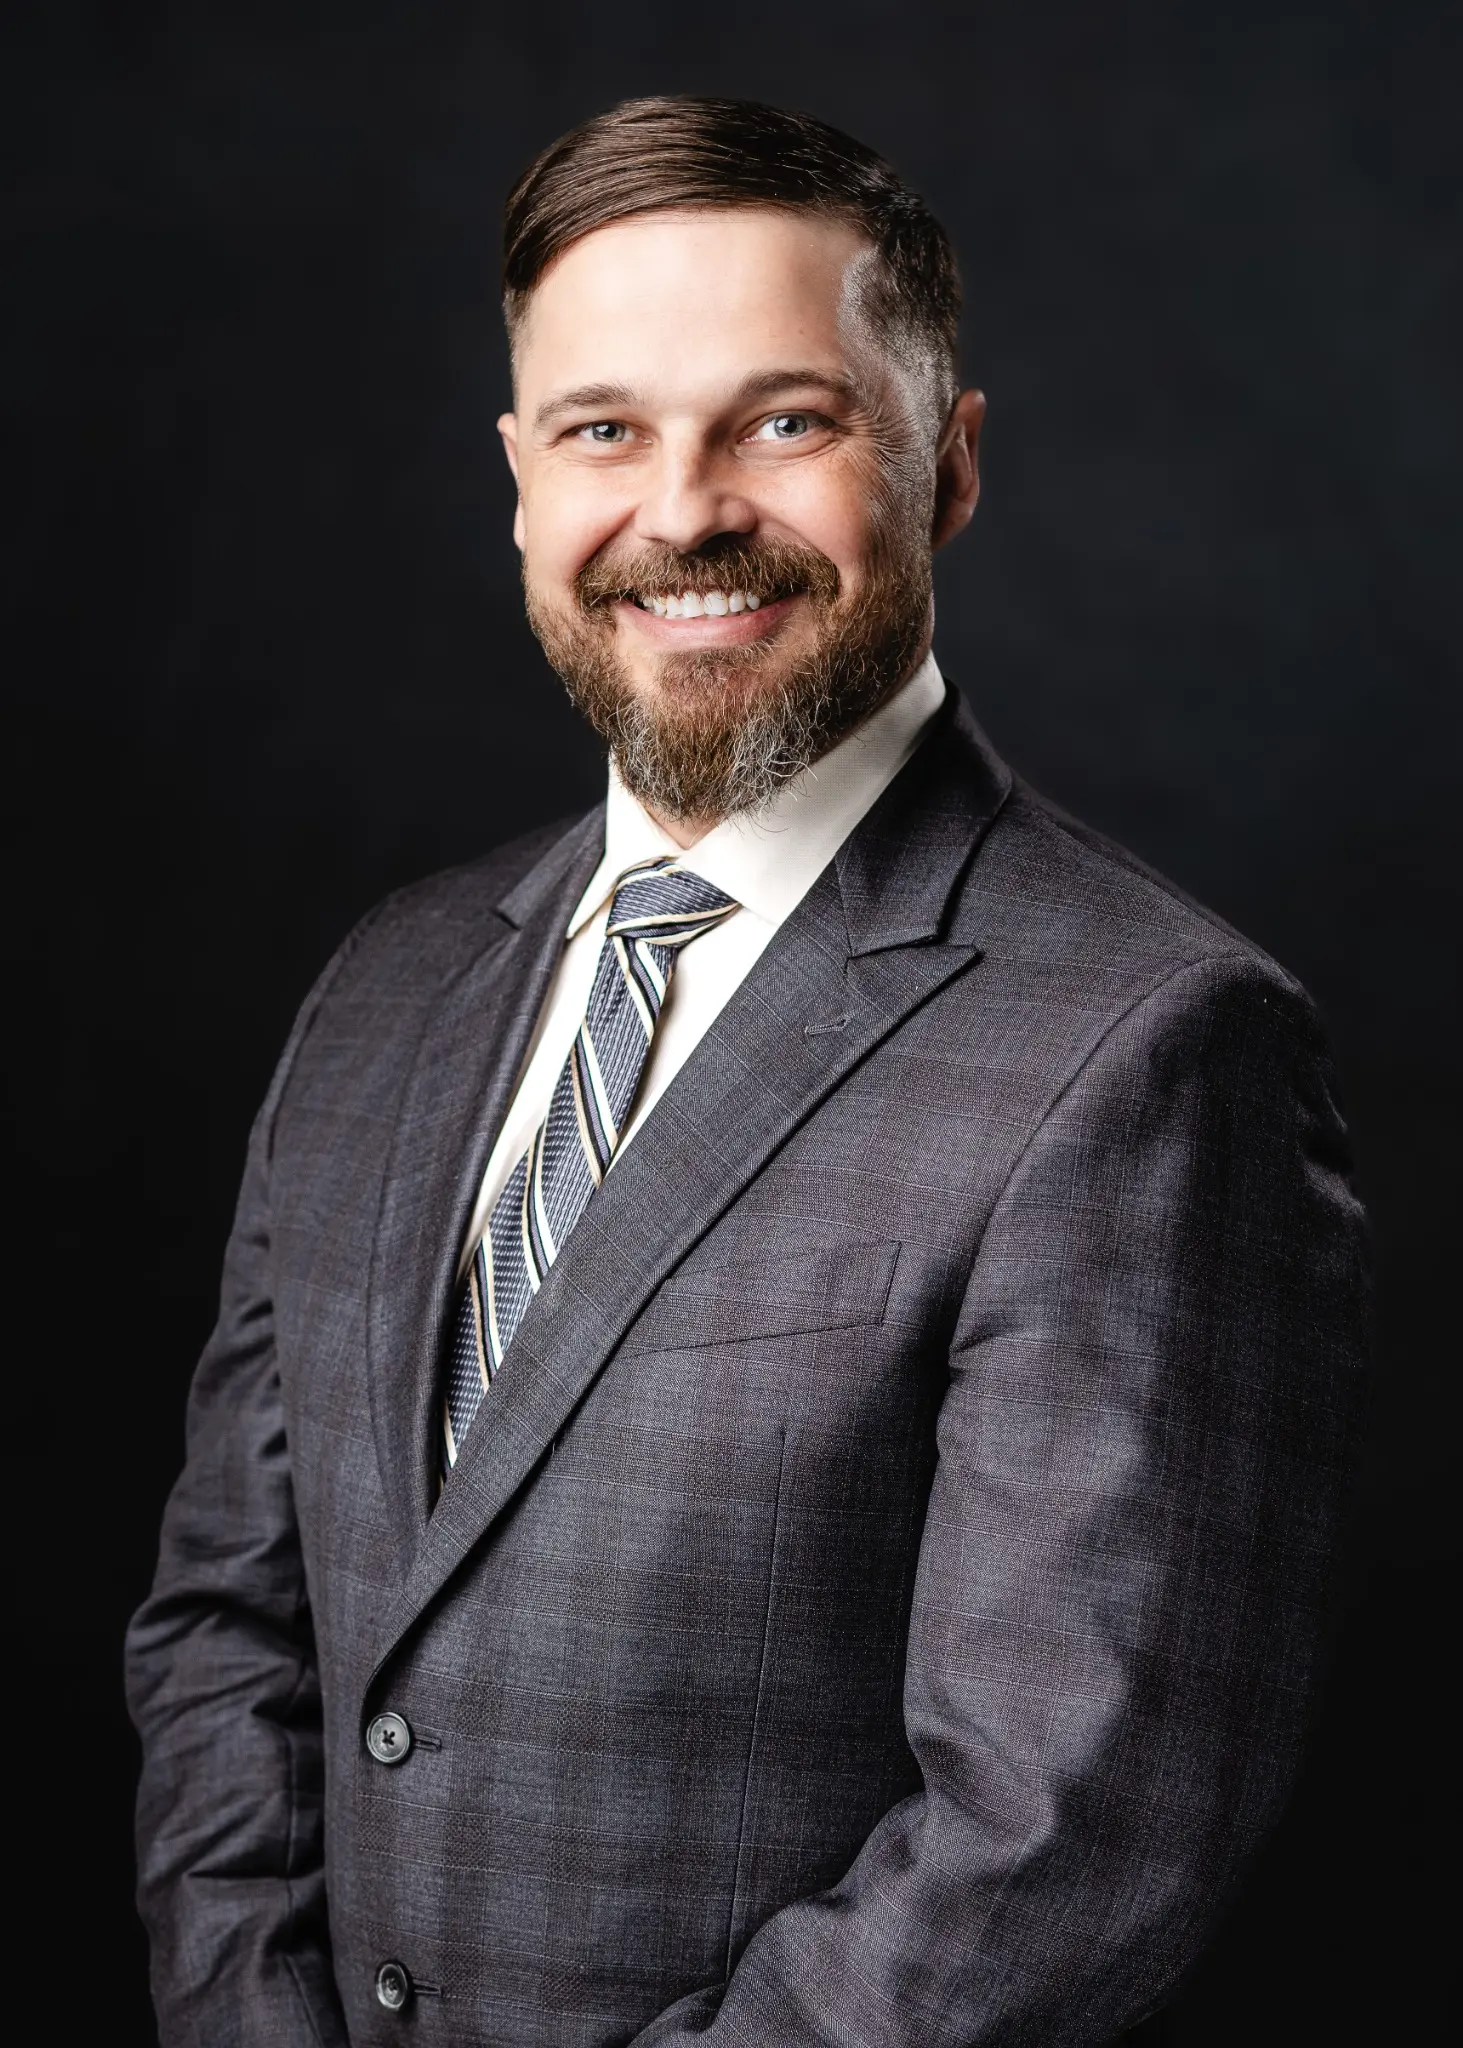
Founder / Lead Attorney
Helps clients with insurance disputes, property damage, and injury claims — understanding what matters, what to document, and how to move forward when a claim becomes disputed or overwhelming.
Focus: insurance, property damage & injury
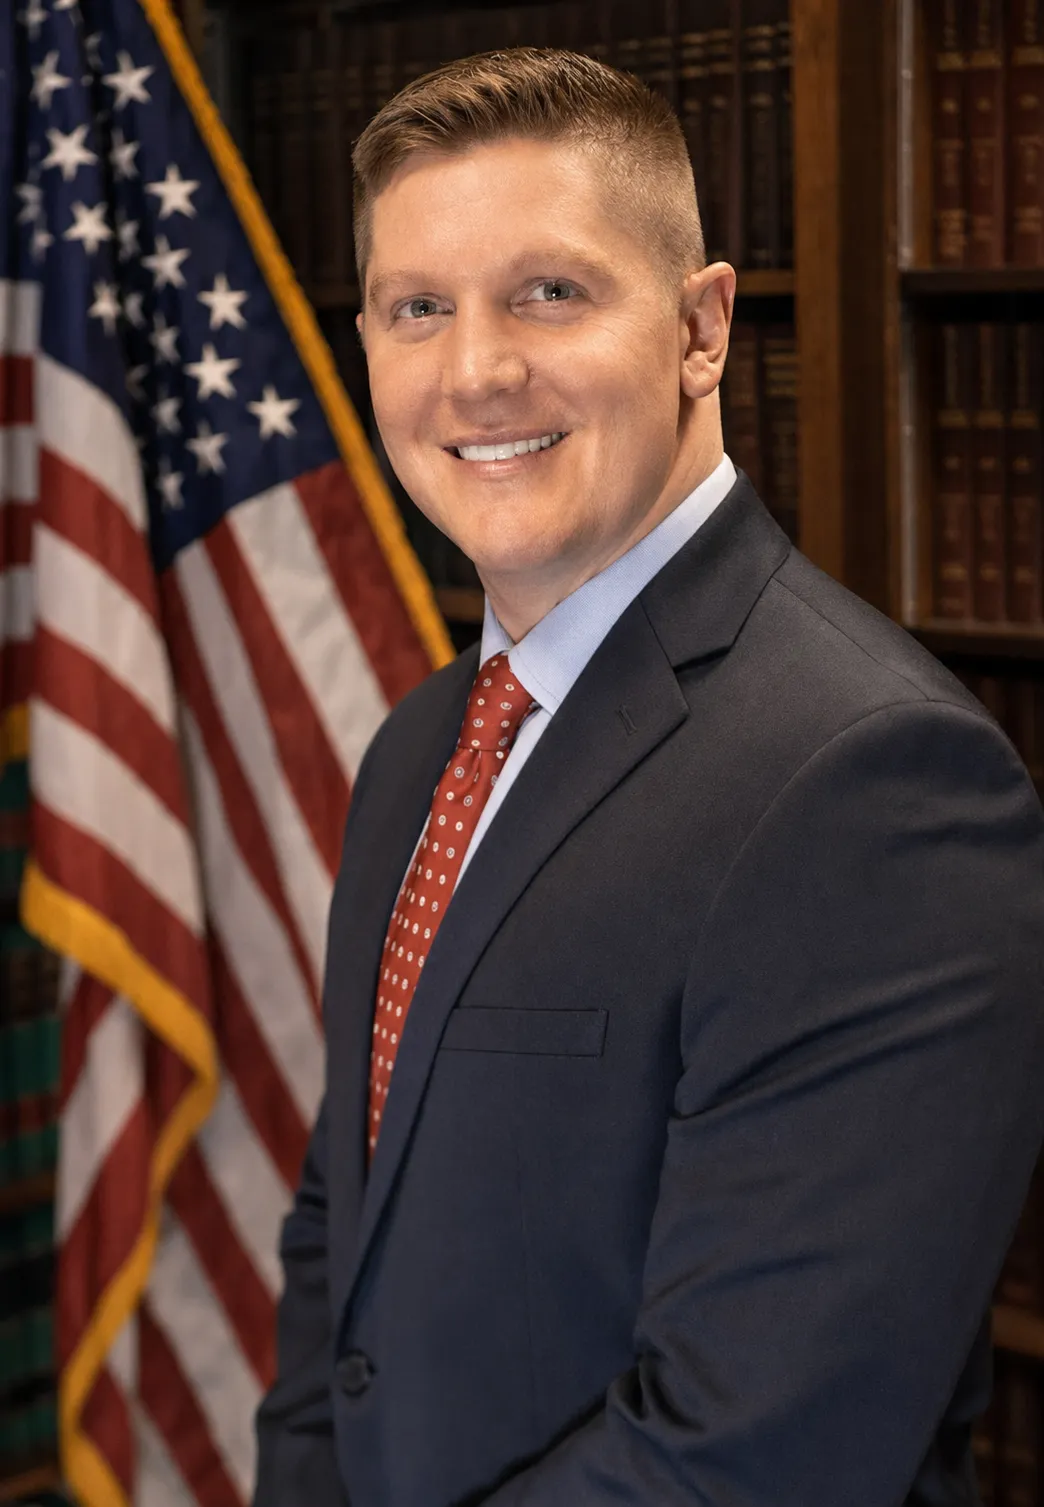
Attorney at Law
Focuses on the details that often matter most: documents, communications, timelines, proof of damage, and the insurance company's positions.
Focus: insurance, property damage & injury
Start here
You do not need to know the exact claim category before reaching out. Start with a free claim review and tell us what happened.
Free review · FL & TN offices
Start Free ReviewClient reviews
A few words from people who needed answers, direction, and help with an insurance claim.
Find the right insurance page
Answer three quick questions and we will point you to the page built for your state, city, and type of claim.
Our offices
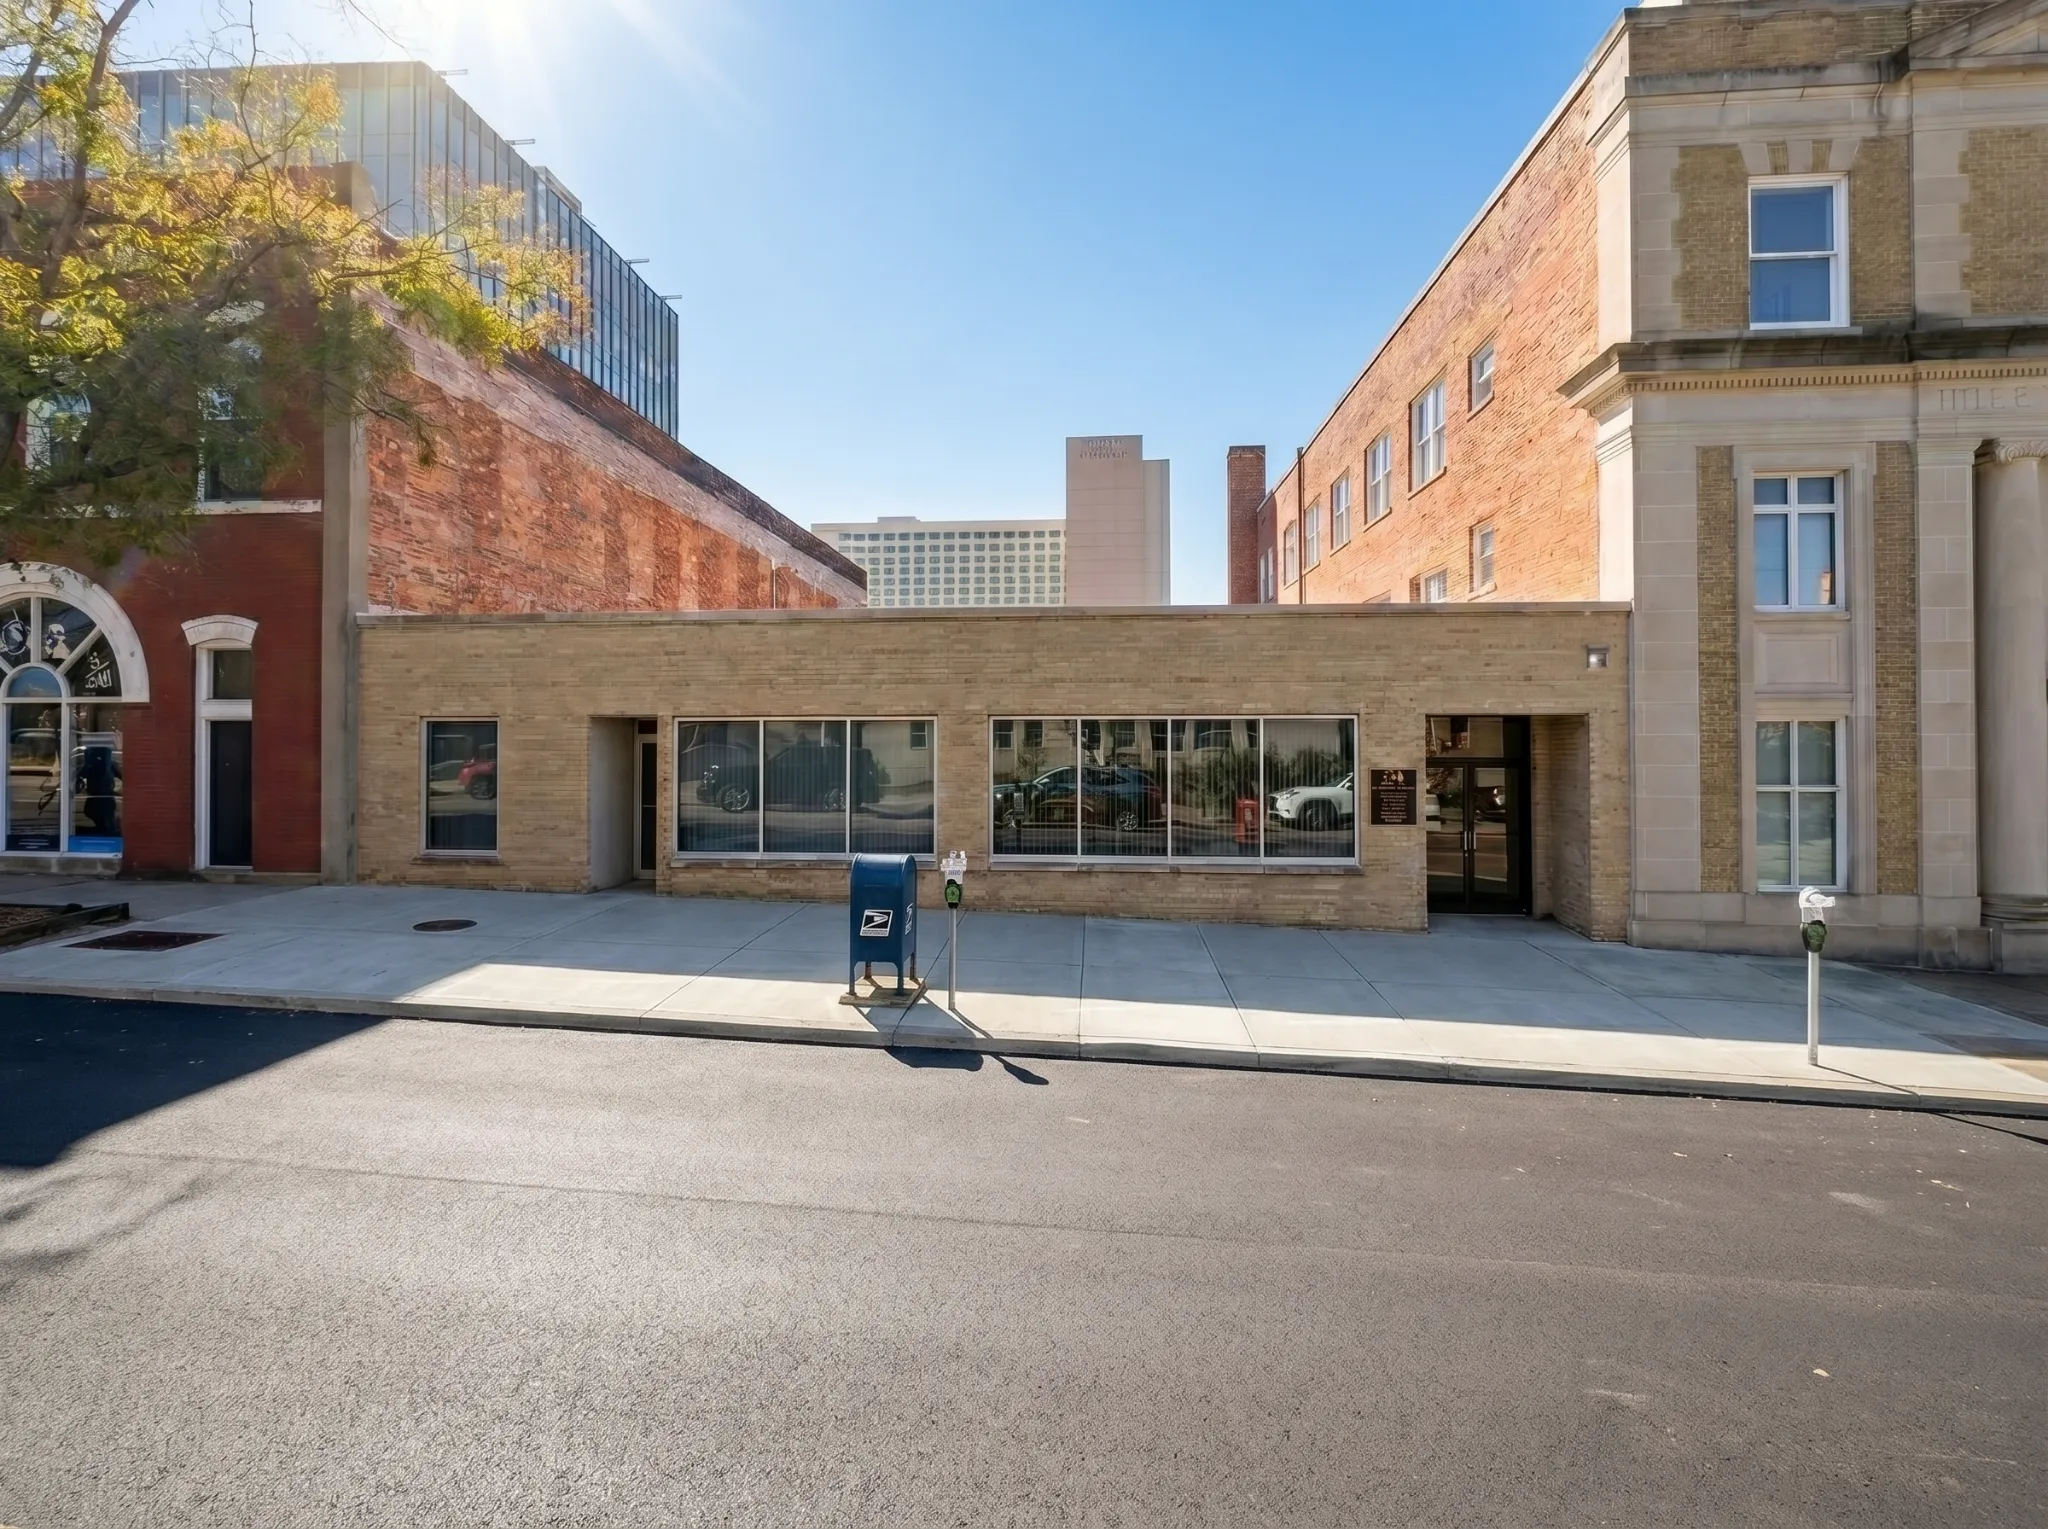 Florida
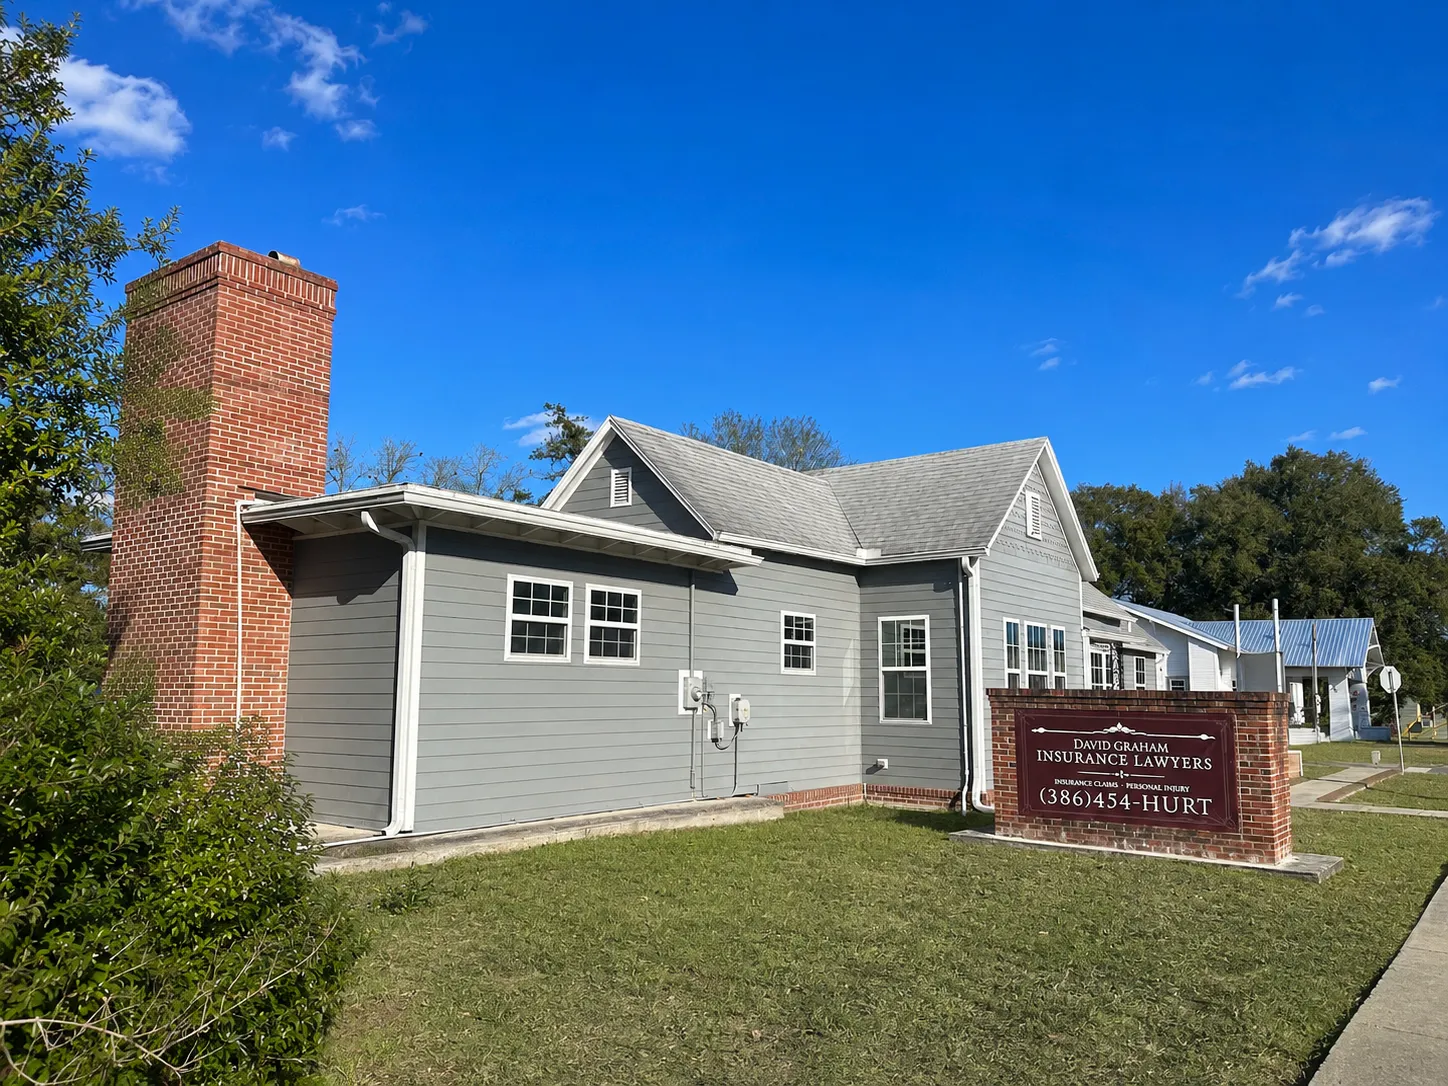 Florida
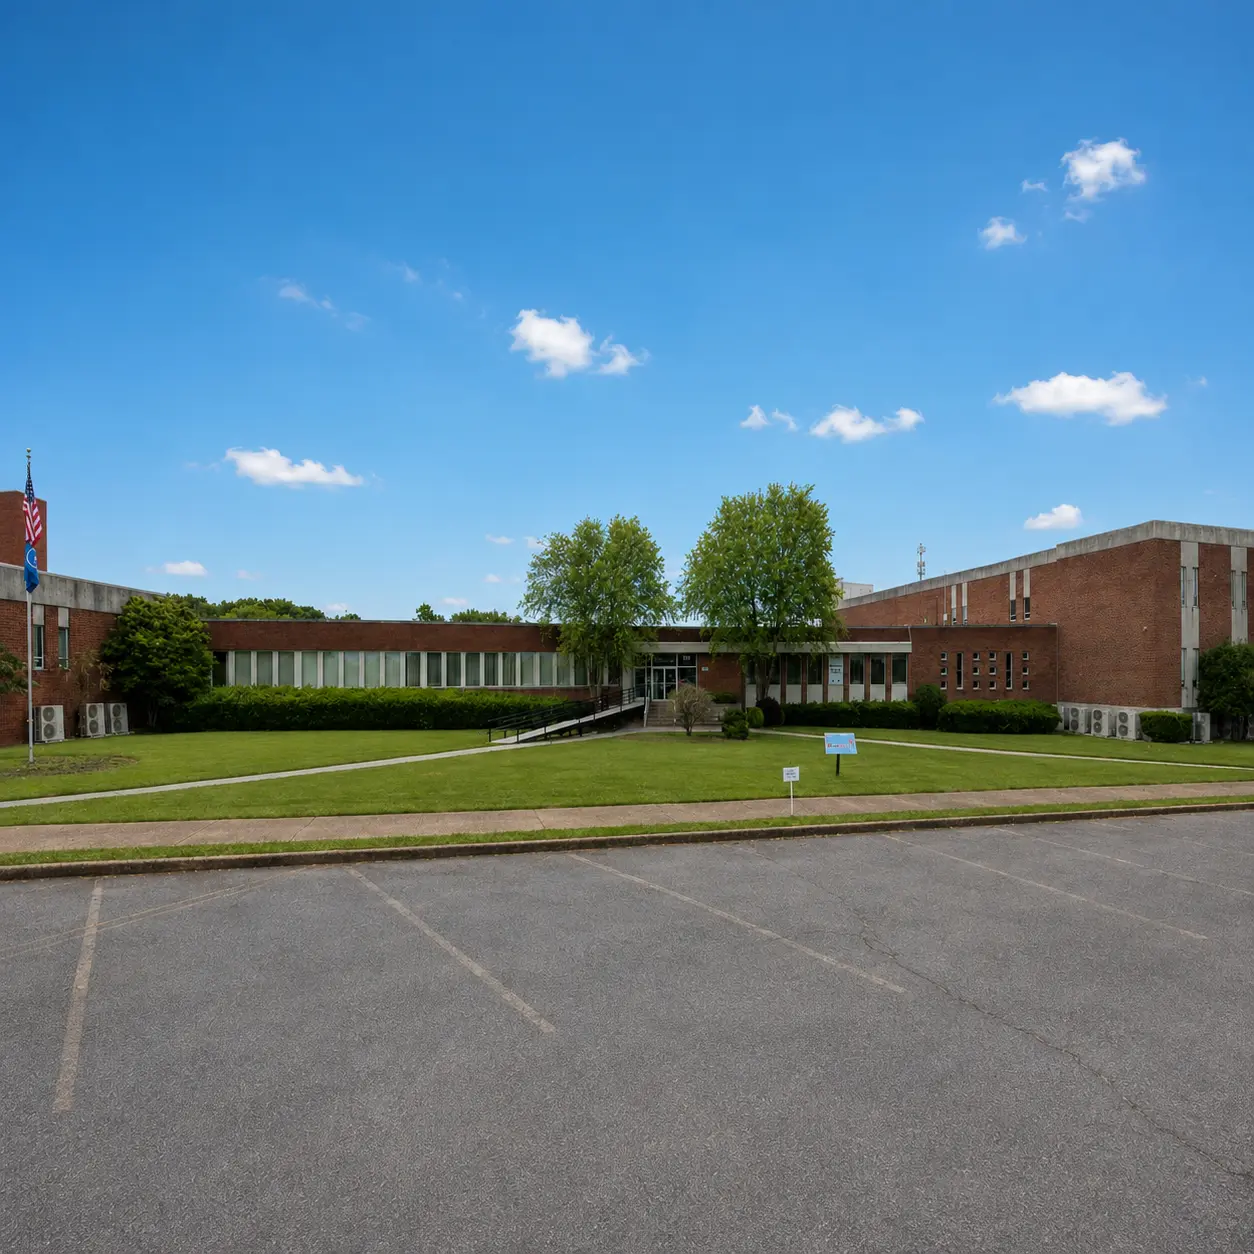 Tennessee
Areas served: Jacksonville, Duval County, Orange Park, Ponte Vedra, St. Augustine, the Beaches, and North Central Florida; Cleveland, Bradley County, Chattanooga, and Southeast Tennessee. Clients in surrounding areas are served remotely where there is no local office.
Free claim review
Tell us what happened, what type of claim it is, where the property or claim is located, and what the insurance company has said so far.
Start here
Insurance claim FAQ
Many people call after a claim is denied, delayed, underpaid, or disputed, or when the insurance company asks for more information before paying. A free review can help you understand whether the issue is routine or a sign of a larger problem.
Yes. Early guidance can help you understand what to document and how to respond before the insurance company defines the claim.
A denial should be reviewed against the policy language, exclusions, facts, inspection findings, and claim history. A denial letter is a starting point for review, not always the final word.
Underpayment often turns on repair scope, estimates, hidden damage, and code requirements. A supplemental claim and independent documentation may support a higher figure.
Delay can be a sign that a claim needs documentation, pressure, or legal review. Organizing the claim record and communications is often the first step.
Wear-and-tear and maintenance arguments should be weighed against damage photos, history, inspection findings, and the cause of loss before they are accepted.
Yes. The firm helps with residential and commercial property claims, including storm, fire, water, roof, mold, and business-interruption losses.
Free case review. No upfront cost to find out whether we can help. If the firm can assist, next steps and any fee arrangement are explained before you decide whether to move forward.
Insurance claim problem?
Tell us what happened, what the insurance company said, and where the claim is located. We can help you understand the next step.